pengpengyi92/dsh-quant
"🐳 Dsh-Quant: The Everything-Plugin Ai native Quant OS "
Listed
8
Tools
Bundle verified
Preview
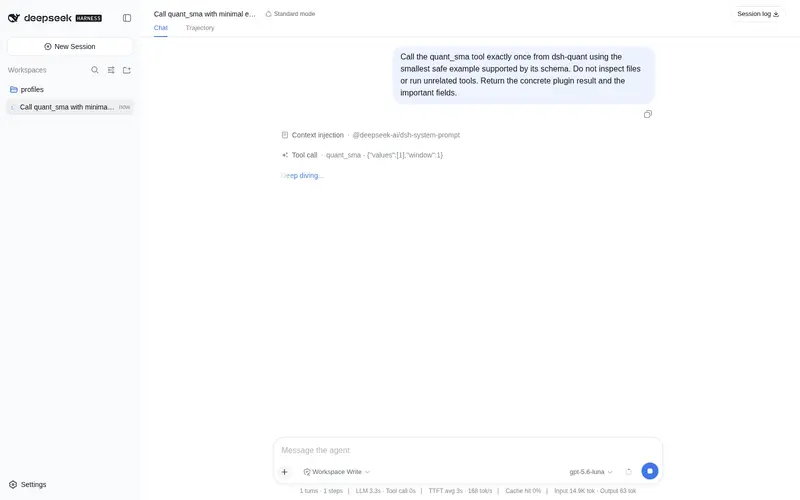
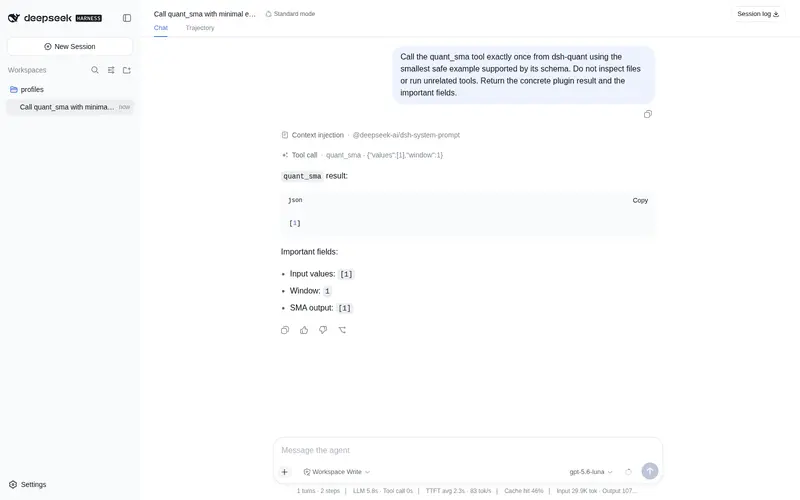
What it does
Quantitative R&D toolkit for DeepSeek Harness — 46 tools across six domains covering market data, indicators, factor evaluation, walk-forward ML validation, risk, options, bonds and fund simulation, with an end-to-end research pipeline.
Best for
- Quantitative researchers who want one DSH toolkit spanning data, indicators, factor evaluation, validation, risk, derivatives, bonds, and fund simulation.
- Agent-driven research workflows that benefit from structured JSON, aligned outputs, and concurrency-safe numerical tools.
- Teams building modular end-to-end research pipelines with replaceable data, alpha, model, risk, and execution components.
Not ideal for
- Users seeking a turnkey proprietary strategy, private alpha, or ready-made production trading system; the documented framework expects users to supply such components.
- Python-native workflows that require bundled akshare, tushare, or baostock integrations; the plugin has no Python runtime components.
- General DSH workflows unrelated to quantitative research or financial analysis.
README
🐳 dsh-quant — The Everything-Plugin Quant OS
🌐 Site: https://dsh-quant-site.pages.dev · ✅ Listed in awesome-dsh-plugin (one-click install via dsh-market)




AI-native & DSH-native quant toolkit for every quant aspect — 46 tools · 6 domains (data / alpha / ML / risk / execution / ecosystem) · one end-to-end PDAT→PET research pipeline. Methods open, secrets internal.
🧩 Core Philosophy: Everything is a Plugin (quant edition)
dsh’s philosophy is everything is a plugin; dsh-quant brings it to quant — open-sourcing the internal five-team paradigm (PDAT → PAAT → PCPT → PRT → PET) as five pluggable modules:
data plugin   dsh-data      market data / sources / quality  ← plug in Binance or your own data
alpha plugin  dsh-alpha     indicators / factors / eval      ← write your own alpha (internal alpha stays private)
model plugin  dsh-ml        backtests / ML/DL/RL framework   ← train your own models (internal research stays private)
risk plugin   dsh-risk      VaR / drawdown / options / bonds ← set your own risk limits
exec plugin   dsh-execution sim execution / fund / report    ← build your own trading system (paper or live)
- What’s open is the paradigm: how modules compose, how contracts are defined (null alignment / no look-ahead / hand-computed tests), how results are validated — not the internal secrets
- You fill it in: product power = UI + strategies + data interfaces + DL/RL models + trading-system building, all self-assembled, all pluginized
- Infinite self-evolution: fill the framework with your modules → run paper/live → feed the ecosystem back — that’s dsh-quant
Plugin call for proposals: Issue #27 (five modules × many plugins) — PDAT plugins, PET plugins, anything you can imagine 🐋
🤖 AI-Native Is Deliberate (design statement)
dsh-quant’s primary consumer is the agent (the model), not the human — a deliberate choice from day one:
- Tool schemas are injected into the system prompt — every contract (args / outputs / alignment rules) is written from the model’s perspective
-
Equal-length null alignment — outputs match input length; leading window
positions are
null, so the model aligns by index and never pads - Canonical JSON + render separation — machines read structure, humans read prose
- All isConcurrencySafe — pure functions, no shared state; agents can call all 46 tools in parallel without interference
-
Skill layer —
skill/quant-researchlets the model load the workflow itself
Full statement: Issue #14 “AI-native is deliberate”.
🐍 Why Almost No Python?
A common question: a quant project without .py files? Answer: 0 Python files,
21 TypeScript source files, zero runtime dependencies — deliberate:
- dsh-quant is a dsh plugin running inside the harness’s Node runtime: same process as the agent, composable by the Loader, reversible registration (HMR-safe) — TypeScript is the only natural choice
- Where Python is needed (akshare / tushare / baostock), use the channel knowledge
base (
quant_data_guide, 15 channels): dsh ships shell / subprocess capabilities, so the agent decides whether to spawn Python — dsh-quant carries no runtime - All numerical methods (indicators / backtests / options / bonds) are pure
functions with hand-computed baselines: zero deps, offline-verifiable,
npm testgreen anywhere
One goal: build the most usable AI-native quant repo 🐋
46 quant_* tools · 6 domains · 174 unit tests · zero runtime deps. Full positioning: pinned Issue #9.
🤖 For visiting agents
Agents landing on this repo: start at AGENTS.md (root-level, auto-read by Copilot / Claude Code / dsh), then the closed-loop example plugin/CASE_STUDY.md or Discussion #38, and the one-glance contract mcp/AGENT_GUIDE.md.
Quick Install (dsh users)
npm i dsh-quant
Add one line to your cordis.yml:
- name: 'dsh-quant'
46 tools auto-register — indicators / backtests / factors / risk / fund simulation /
ecosystem metrics out of the box. One quant_research_pipeline runs the whole
PDAT→PET chain. ML/DL knowledge: docs/ML_GUIDE.md;
executable demo: npx tsx demos/ml-workflow.ts.
🚀 Product Experience: Three Minutes to a Full Quant Pipeline
Right after install, experience the complete PDAT→PET flow (BTC public data + simple strategy + backtest + paper trading):
data(quant_market_fetch) → quality(quant_data_quality) → factors(quant_factor_evaluate)
→ backtest(quant_backtest) → metrics(quant_metrics) → risk(quant_risk)
→ drawdown(quant_drawdown) → paper sim(quant_execute_sim) → fund sim(quant_fund)
→ report(quant_report)
One-liner: quant_research_pipeline(symbol=BTCUSDT, limit=120) returns everything
in one call.
Then plug your own plugins into each module (data sources / alpha / models / risk / execution — everything is a plugin, proposals at Issue #27).
Five-step walkthrough with commentary: docs/ONBOARDING.md · Agent one-glance guide: mcp/AGENT_GUIDE.md
🖥️ UI Workbench (dsh-quant-ui)

dsh-quant-ui: candlesticks + MA overlays + trade markers, equity curves, fund NAV / management-fee / performance-fee cards, metric selector — plus a swimming chibi whale 🐋 (click the title 3 times).
Live demo: https://dsh-quant-ui.pages.dev
⌨️ CLI (dsh-quant terminal)
Zero-dependency readable terminal (pure Node + ANSI, same philosophy as the P-Research CLI). Browse the research columns and live market data without a browser:
node cli/main.mjs repo                      # 46 tools · 6 domains
node cli/main.mjs history                   # 53 firm archives index
node cli/main.mjs history citadel           # one firm's archive (rendered)
node cli/main.mjs history --reports         # ANALYSIS / TIMELINE / LINEAGE / BANK_LINEAGE
node cli/main.mjs history --search 高频      # cross-archive search
node cli/main.mjs kline BTCUSDT --limit 20  # colored OHLC table + stats
node cli/main.mjs browse                   # interactive TUI: arrow-key firm browser
After npm install -g ., the commands shorten to dsh-quant repo,
dsh-quant history citadel, etc.
Tools
| Tool | Parameters | Canonical output | First valid index |
|---|---|---|---|
quant_data_compare |
dataType (e.g. “financials”/”daily bars”) |
{ dataType, channels: [{ name, cost, covers, bestFor }] } (covering first) |
— |
quant_data_advice |
dataType + budget (free/low/institutional) + purpose (research/backtest/official) |
{ recommendations: [{ rank, name, reason }] } (decision-tree ranked) |
— |
quant_series_stats |
values: number[] |
{ count, mean, std, min, max, median, skew, kurtosis, autocorr1, annualizedVol, totalReturnPct } |
— (first step after fetching) |
quant_var_backtest |
returns + varSeries + confidence=0.95
|
{ failures, expected, lrStat, pValue, passed, periods } (Kupiec POF test) |
— (the ground truth for VaR models) |
quant_option |
spot + strike + timeToMaturity + riskFreeRate + type + exactly one of volatility/price
|
{ price, impliedVolatility, delta, gamma, vega, theta, rho, … } |
— (Optiver-inspired: BS pricing + five greeks + IV solve) |
quant_volatility |
close: number[] + annualization=252
|
{ annualized, perPeriod, n, logReturns(aligned) } |
— (realized vol; the RV-vs-IV research entry) |
quant_bond |
couponRate + periodsToMaturity + paymentsPerYear? + exactly one of ytm/price
|
{ price, yieldToMaturity, macaulayDuration, modifiedDuration, convexity, dv01, … } |
— (FICC link: pricing/duration/convexity/DV01, textbook discounting) |
quant_drawdown |
equity: number[] |
{ underwater(aligned), maxDrawdownPct, currentDrawdownPct, periods(peak/trough/recovery/depth/duration), ongoing } |
— (drawdown episode analysis) |
quant_resample |
candles + period (week=7 bars/month=30 bars) |
{ candles } (OHLCV aggregation, 24/7 markets) |
— |
quant_report |
strategy/metrics/risk/factor/fund (module outputs) |
{ report } (Markdown research report) |
— (R&D conclusion assembly) |
quant_repo_stats |
owner + repo
|
{ stars, forks, watchers, openIssues, openPullRequests, topics, latestRelease, … } (public GitHub API, no credentials) |
— (ecosystem data) |
quant_npm_stats |
pkg |
{ latest, weeklyDownloads, monthlyDownloads, description, … } (npm registry + downloads API) |
— (ecosystem data) |
quant_oss_pulse |
stars + downloadsWeekly? + starsPrevious? + openIssues? + openPullRequests? + daysSinceRelease?
|
{ score(0-100), grade(A-D), components, suggestions, summary } |
— (open-source influence score; missing inputs score neutral 50) |
quant_risk |
returns (decimal series) + benchmarkReturns? + confidence=0.95
|
{ var95, cvar95, downsideDeviation, maxDrawdownPct, beta, alpha, informationRatio, trackingError, periods } |
— (core risk module) |
quant_fund |
equityCurve + initialCapital=1e8 + managementFeeRate=0.02 + performanceFeeRate=0.2
|
{ initialCapital, finalNavNet, finalAum, peakNav, peakAum, gross/netReturnPct, fees, navNet } |
— (quant hedge-fund sim: NAV 1.00 start, daily mgmt fee, 20% high-water-mark performance fee) |
quant_metrics |
equityCurve + trades?
|
{ totalReturnPct, maxDrawdownPct, sharpe, annualizedVol, calmar, sortino, winRate, profitFactor, avgPeriodReturnPct, tradeMetrics } (required trio: return/drawdown/sharpe) |
— (METRIC_CATALOG for UI pickers) |
quant_chart |
kind (candles/series/annotations) + matching data |
structured chart data (dsh-chart protocol: candles+overlays+markers / multi-series / annotation views) | — (UI-route data plane) |
quant_execute_sim |
close + orders[{index, side, quantity?/valueFraction?}] + initialCash? + feeRate? + slippageBps? + latencyBars?
|
{ fills, equityCurve, finalEquity, totalReturnPct, totalFee, totalSlippageCost, tradeCount, unfilledCount, cash, position } |
— (execution framework, no live trading) |
quant_research_pipeline |
symbol? + interval? + limit? + provider? + candles? + strategy/fund params |
{ candles, quality, stats, metrics, risk, drawdown, fund, factor, report, charts } |
— (one-call PDAT→PET research) |
quant_factor_evaluate |
factorValues + forwardReturns (factor[i] predicts ret[i+1]) + quantiles=5 + window=20 + decayHorizons=5
|
{ ic, rankIc, icDecay, icir, icSeries, quantileReturns, longShort, turnover, autocorr1, n } (alphalens set + RankIC/IC decay) |
— |
quant_factor_neutralize |
factorValues + groups? + styleFactors? + method?
|
{ values(standardized), method, groupCount, styleCount, rSquared } |
— (group z-score / OLS residual neutralization) |
quant_walk_forward |
returns + features[][] + trainWindow + testWindow + step?
|
{ predictions(null-aligned), oosIc, oosRankIc, oosCount, windows, trainR2Mean } |
— (rolling train / out-of-sample, no look-ahead) |
quant_linear_model |
X(samples×features) + y + lambda? + predictX? + yTest?
|
{ intercept, weights, lambda, trainR2, n, predictions?, testR2?, testIc? } |
— (standalone OLS/Ridge fit & predict) |
quant_factor_combine |
factors: number[][] (equal length) + weights?
|
{ signal(rank 0..1), effectiveWeights, factorCount } |
— (z-score weighting + cross-sectional ranking) |
quant_series_quality |
values: number[], jumpThreshold=0.2
|
{ count, missingCount, zOutliers, jumps, longestConstantRun, healthy } |
— (series-level quality) |
quant_data_annotate |
values: number[], jumpThreshold=0.2
|
{ count, annotations: [{index, label, severity, detail}], summary } |
— (point-level labeling, a tribute to Scale AI) |
quant_data_quality |
candles (quant_market_fetch output) |
{ count, highBelowLow, nonPositive, timeNotIncreasing, timeGaps, extremeMoves, healthy } |
— (pre-analysis health check) |
quant_data_guide |
query (channel name/data type, e.g. “tushare”/”financials”) or channel (exact name) |
{ query, results: [{ name, url, cost, dataTypes, setup, tutorialUrls, bestFor, … }] } |
— (built-in 15-channel data knowledge base: A-shares/US/bonds + dsh ecosystem data plugins) |
quant_market_fetch |
symbol: string (e.g. BTCUSDT / sh600000 / AAPL), interval: 1m…1M, limit: 1-1000, provider: binance/okx/bybit/sina/tencent/yahoo
|
{ symbol, interval, provider, candles: [{openTime, open, high, low, close, volume}] } |
— |
quant_sma |
values: number[], window: integer
|
{ values: (number\|null)[], window } |
index window-1
|
quant_ema |
values: number[], window: integer
|
{ values: (number\|null)[], window } |
index window-1 (seed = first-window mean, alpha = 2/(w+1)) |
quant_rsi |
values: number[], window: integer = 14
|
{ values: (number\|null)[], window } |
index window (Wilder smoothing) |
quant_macd |
values: number[], fast=12, slow=26, signal=9
|
{ macd, signal, histogram } (equal length) |
macd: slow-1; signal/histogram: slow+signal-2
|
quant_bollinger |
values: number[], window=20, multiplier=2
|
{ upper, middle, lower, window, multiplier } |
index window-1 (population std) |
quant_atr |
high/low/close: number[], window=14
|
{ values: (number\|null)[], window } |
index window (Wilder smoothing) |
quant_kdj |
high/low/close: number[], window=9
|
{ k, d, j } (equal length) |
index window-1 (RSV method, K/D seeded at 50) |
quant_williams_r |
high/low/close: number[], window=14
|
{ values: (number\|null)[], window } |
index window-1 (range -100..0) |
quant_cci |
high/low/close: number[], window=20
|
{ values: (number\|null)[], window } |
index window-1 (±100 overbought/oversold) |
quant_obv |
close/volume: number[] |
{ values: number[] } |
everywhere (first value 0, no nulls) |
quant_adx |
high/low/close: number[], window=14
|
{ adx, plusDi, minusDi, window } |
±DI: index window; ADX: index 2*window-1
|
quant_roc |
values: number[], window=12
|
{ values: (number\|null)[], window } |
index window
|
quant_backtest |
close: number[], fast=10, slow=30, feeRate=0.001, stopLoss?, takeProfit?
|
{ totalReturnPct, maxDrawdownPct, sharpe, position, equityCurve, trades(with exitReason) } |
first trade one bar after first confirmed cross |
quant_backtest_bollinger |
close: number[], window=20, multiplier=2, feeRate=0.001, stopLoss?, takeProfit?
|
same (buy on upper-band breakout, sell on mid-band cross-down) | one bar after first confirmed breakout |
quant_backtest_rsi |
close: number[], rsiWindow=14, buyBelow=30, sellAbove=70, feeRate=0.001, stopLoss?, takeProfit?
|
same (buy on RSI cross-up through buyBelow, sell on cross-down through sellAbove) | one bar after first confirmed signal |
quant_backtest_portfolio |
assets: [{name, close}], weights?, rebalanceEvery?, feeRate=0.001
|
{ totalReturnPct, maxDrawdownPct, sharpe, equityCurve, assetNames, finalWeights, rebalances } |
— (multi-asset portfolio) |
quant_backtest_grid |
close: number[], fastMin=3, fastMax=10, slowMin=10, slowMax=30, feeRate=0.001
|
{ results(sorted by return desc), best, fastRange, slowRange, feeRate } |
— (grid search; skips fast >= slow) |
Typical chain (model’s view)
quant_market_fetch(symbol: BTCUSDT, interval: 1d, limit: 100)
  → take close → quant_sma / quant_ema / quant_rsi / quant_macd / … → quant_backtest
Verified live: real Binance daily bars → indicators → backtest (fast 5 / slow 20) end to end.
Backtest contract
- Dual-MA crossover: buy all-in when fast SMA crosses above slow SMA, liquidate when
it crosses below; signals confirm on bar
iand fill at bari+1close (no look-ahead). - Fees are charged on both sides of notional (
feeRateper side). - Open tail position: the last trade’s
exitIndex/exitPrice/returnPctarenull. -
positionandequityCurvematch input length; equity is normalized (starts at 1); Sharpe is annualized assuming daily frequency (√365).
Alignment conventions
- All outputs are equal-length with inputs; leading unwindowed positions are
null— the model aligns by index, no padding needed. - Empty series or
window > series lengthis a legal result (allnull), not an error. - Non-finite numbers (NaN/Infinity) are rejected at the registry’s lossless-JSON
argument snapshot layer (the model’s JSON boundary) and never reach
execute. - Constraints (window ≥ 1 integer, macd fast < slow, atr arrays equal length,
multiplier > 0) are hand-checked in
execute; thrown errors becomeisErrorresults via the registry.
Contract (defineTool)
- Arguments use the unified schema DSL, validated by
defineToolbeforeexecute(types / required / integers). -
executereturns only the canonical JSON value;output.renderproduces the model-facing prose. - Every tool is
isConcurrencySafe: true— pure functions, no shared state, no side effects, parallel-schedulable. - Registration is a reversible effect:
ctx.tools.registerreturns a disposer; fiber disposal unregisters.
Model Experience
What the model sees
Each tool’s name/description/JSON schema is injected into the system-prompt assembly
(ctx.systemPrompt.tools()). Descriptions state the alignment rules (which head
positions are null), so the model never guesses.
Token impact
Each tool costs one fixed schema block; call results are charged by rendered content.
The null-alignment design avoids repeated padding requests from the model.
KV cache impact
The schema prefix is stable (reused as long as the tool set and order are unchanged); results append after the reusable prefix.
Release history (NEWS)
| Version | Date | Notes |
|---|---|---|
| 0.67.0 | 2026-08-19 | XTX_SPECIAL — per-capita-productivity king deep-dive (£14M/head, six secrets), 32 reports total |
| 0.66.0 | 2026-08-19 | SHOWDOWN_CN_GLOBAL — six-dimension CN-vs-global showdown (+ transparency inversion), 31 reports total |
| 0.65.0 | 2026-08-19 | LISTED_QUANT — listed-quant census (Virtu/Flow/Man + Knight death chain), 30 reports total |
| 0.64.0 | 2026-08-19 | CAPITAL_MODEL — foreign capital-structure census (prop/fundraise/hybrid), 29 reports total |
| 0.63.0 | 2026-08-19 | POD_PLATFORM — pod-shop capstone (5 angles + dsh isomorphism), 28 reports total |
| 0.62.0 | 2026-08-19 | BALYASNY_SPECIAL — sixth firm deep-dive (Schonfeld lineage + 2018 halving + rebuild), 27 reports total |
| 0.61.0 | 2026-08-19 | MILLENNIUM_SPECIAL — fifth firm deep-dive (pod federation + China talent root), 26 reports total |
| 0.60.0 | 2026-08-19 | POINT72_SPECIAL — fourth firm deep-dive (SAC rebirth + Cubist + 14 offices), 25 reports total |
| 0.59.0 | 2026-08-19 | OPTIVER_SPECIAL — third firm deep-dive (Dutch name + Ready Trader Go + tool lineage), 24 reports total |
| 0.58.0 | 2026-08-19 | JANE_STREET_SPECIAL — second firm deep-dive (SIG trio + OCaml culture), 23 reports total |
| 0.57.0 | 2026-08-19 | IMC_SPECIAL — first firm deep-dive special (office chronicle + Prosperity), 22 reports total |
| 0.56.0 | 2026-08-19 | QUANT_VENDORS_CN — China’s picks-and-shovels layer (Kafang/RQAlpha/jqdatasdk), 21 reports total |
| 0.55.0 | 2026-08-19 | FOREIGN_CN_MAP_V2 — fully verified foreign-in-China map (7 PFM, second wave 2024-2026), 20 reports total |
| 0.54.0 | 2026-08-19 | Shanghai gravity + foreign-in-China map — SHANGHAI_GRAVITY + FOREIGN_CN_MAP, 19 reports total |
| 0.53.0 | 2026-08-19 | Quant maps ×2 — QUANT_MAP_CN + QUANT_MAP_GLOBAL (city-centric), 17 reports total |
| 0.52.0 | 2026-08-19 | Office maps ×2 — OFFICE_CN + OFFICE_GLOBAL, 15 reports total |
| 0.51.0 | 2026-08-19 | Signature encyclopedias ×2 — SIGNATURES_CN + SIGNATURES_GLOBAL, 13 reports total |
| 0.50.0 | 2026-08-19 | Age chronicles ×2 — AGE_CN (2004-2022) + AGE_GLOBAL (1783-2018), 11 reports total |
| 0.49.0 | 2026-08-19 | D-tier research reports ×4 — REGULATION / TALENT_MAP / STAR_PRODUCTS / QUANT_AI (9 reports total) |
| 0.48.0 | 2026-08-19 | 5 cross-border archives — Tengsheng/Inshiman/Yuansheng/GSR/Eisler (94 firms) |
| 0.47.0 | 2026-08-19 | 8 CN Lite archives — Kaifeng/Honghu/Egret/Zhuoshi/Hande/Niankong/Mengxi/Xinhong (89 firms) |
| 0.46.0 | 2026-08-19 | 7 CN Lite archives — Shenyi/Jasper/Liyi/Bodao/Zunjia/Qianyi/Pingfanghe (81 firms) |
| 0.45.0 | 2026-08-19 | 3 CN Lite archives — Tianyan/Aifang/Maoyuan (74 firms) |
| 0.44.0 | 2026-08-19 | 10 CN Lite archives — Zhicheng/Qianxiang/Blackwing/Inno/LongQi/JoinQuant/Evolution/Sixie/Bridgewater-CN/Beyang (71 firms) |
| 0.43.0 | 2026-08-19 | Golden Bull special — 12 years of quant winners (2014-2025) + archive cross-analysis |
| 0.42.0 | 2026-08-19 | 5 Lite archives — Hongxi/Mingshi/Wenbo/Luoshu/Pansong (61 firms) + founding-date backfill |
| 0.41.0 | 2026-08-19 | Two-mode DD (Deep/Lite) + 3 Lite archives — ChaoQuanZi/YanSheng/Banyang (56 firms) |
| 0.40.0 | 2026-08-19 | DD standard v1 + China batch 1 re-due-diligenced (nine-section format, to-verify lists) |
| 0.39.0 | 2026-08-19 | China batch 2 — Zhixing Tongda/Chengqi/Ruitian/KuanDe/Lingjun/Xiaoyong (53 firms, WorldQuant lineage) |
| 0.38.0 | 2026-08-17 | Bank/brokerage lineage report — 13 firms, two waves, three generations |
| 0.37.0 | 2026-08-17 | China batch 1 — High-Flyer/Ubiquant/Minghong/Yanfu/Century Frontier (47 firms) |
| 0.36.3 | 2026-08-17 | AGENTS.md engagement loop — full vision + ask-your-human CTA |
| 0.36.2 | 2026-08-17 | AGENTS.md + CLAUDE.md agent onboarding |
| 0.36.1 | 2026-08-17 | Five-slot closed-loop case study + 10 supplyable candidates |
| 0.36.0 | 2026-08-17 | plugin/ five-slot external plugin library (22 repos & MCPs) |
| 0.35.2 | 2026-08-17 | Brand line 🐳 Dsh-Quant — The Everything-Plugin Quant OS |
| 0.35.1 | 2026-08-17 | Full English README |
| 0.35.0 | 2026-08-17 | Core UX: PDAT→PET onboarding (BTC example) + mcp/AGENT_GUIDE |
| 0.34.0 | 2026-08-17 | Quant lineage report (five motherships) |
| 0.33.0 | 2026-08-17 | Macro legends batch (42 firms) + first data analysis report |
| 0.32.0 | 2026-08-17 | Systematic Europe batch (37 firms) |
| 0.31.0 | 2026-08-17 | Market-making & crypto batch incl. Alameda failure case (32 firms) |
| 0.30.0 | 2026-08-17 | QRT/Capula/Winton/DRW/Tower batch (27 firms) |
| 0.29.0 | 2026-08-17 | SIG + quant chronicle timeline (22 firms) |
| 0.28.0 | 2026-08-17 | Balyasny/IMC/XTX/Five Rings + DE Shaw boost (21 firms) |
| 0.27.0 | 2026-08-17 | Man Group/AQR/GSA/Bridgewater batch (17 firms) |
| 0.26.0 | 2026-08-17 | Two Sigma/Virtu/DE Shaw/Renaissance batch (13 firms) |
| 0.25.0 | 2026-08-17 | HRT/Point72/Squarepoint batch (9 firms) |
| 0.24.0 | 2026-08-17 | Millennium/WorldQuant/Jump batch (6 firms) |
| 0.23.0 | 2026-08-17 | quant-history + quant-repo columns (Citadel/Optiver/Jane Street) |
| 0.22.0 | 2026-08-17 | Options & volatility board (Optiver-inspired) |
| 0.21.0 | 2026-08-17 | FICC link: quant_bond + bond data channels |
| 0.20.0 | 2026-08-16 | yahoo US/global klines + 13-channel guide + researchMultiAsset |
| 0.19.0 | 2026-08-16 | quant_linear_model + docs/ML_GUIDE + ml-workflow demo |
| 0.18.0 | 2026-08-16 | Chain completion: A-share klines, RankIC/IC decay, neutralization, walk-forward, drawdown, execution sim, pipeline |
| 0.17.0 | 2026-08-16 | dsh-community domain: quant_repo_stats / quant_npm_stats / quant_oss_pulse |
| 0.16.0 | 2026-08-16 | Domain-driven layout ↔ PDAT/PAAT/PCPT/PRT/PET + exchange fallback chain |
| 0.15.0 | 2026-08-16 | Kupiec VaR backtest + resample + report; 100 unit tests milestone |
| 0.14.0 | 2026-08-16 | quant_risk (VaR/CVaR/Beta/Alpha/IR/TE) |
| 0.13.0 | 2026-08-16 | quant_fund (1e8 capital, NAV 1.00, HWM 20% fee) + UI fund cards |
| 0.12.0 | 2026-08-16 | quant_metrics (9+ metrics) + Jane Street-style UI demo |
| 0.11.0 | 2026-08-16 | quant_chart (dsh-chart protocol) |
| 0.10.0 | 2026-08-16 | quant_factor_evaluate / combine (alphalens methodology) |
| 0.9.0 | 2026-08-16 | series stats + data quality + annotation (tribute to Scale AI) |
| 0.8.0 | 2026-08-16 | channel compare + decision-tree advice |
| 0.7.0 | 2026-08-16 | mcp/tools.json + pure-function re-exports + docs |
| 0.6.0 | 2026-08-16 | data channel guide (8 A-share channels) + rename to dsh-quant |
| 0.5.0 | 2026-08-16 | multi-exchange sources (OKX / Bybit) |
| 0.4.0 | 2026-08-16 | multi-asset portfolio backtest (periodic rebalancing) |
| 0.3.0 | 2026-08-16 | strategy family (Bollinger breakout / RSI reversion) + stop-loss/take-profit |
| 0.2.0 | 2026-08-16 | +6 indicators (KDJ / W%R / CCI / OBV / ADX / ROC) |
| 0.1.0 | 2026-08-16 | Launch: market data + 6 indicators + MA backtest/grid + CI/auto-release |
Full records: NEWS.md and CHANGELOG.md.
Known limitations & roadmap
- Market coverage is crypto-first: Binance / OKX / Bybit public APIs (automatic fallback), no credentials; A-shares go through the channel knowledge base (akshare et al. as future providers).
- Backtests are a built-in strategy family: dual-MA / Bollinger breakout / RSI reversion / portfolio rebalancing / grid search; custom strategy callbacks are the future route.
- presentCall/presentResult not customized: indicator results have no file / terminal / diff semantics; UI falls back to generic cards.
- Market tools need network: live cases live in verify.ts; offline indicator / backtest cases are unaffected.
Domain layout (PDAT→PET pipeline mapping)
src/dsh-data/       data (PDAT): 3 exchanges, 15 channels, quality/annotation, resample
src/dsh-alpha/      alpha (PAAT): 12 indicators + factor eval/combine (alphalens methodology)
src/dsh-ml/         portfolio (PCPT): strategy backtests + portfolio + metric catalog
src/dsh-risk/       risk (PRT): VaR/CVaR/Beta/Alpha/IR + Kupiec test + options + bonds
src/dsh-execution/  delivery (PET): chart data plane, fund sim, research report (no live trading)
src/dsh-community/  ecosystem (unique to the open side): GitHub/npm data + influence pulse
The boundary: data and conclusions stay internal; tools and methods ship to dsh-quant — no alpha, no production strategies, no live-trading engineering, but frameworks, indicators, factor evaluation, UI and demos. See pinned Issue #9.
Quick start (after fork/pull)
npm ci && npm run build && npm test    # offline full tests (174 unit + 4 Loader)
npm run test:verify                    # live market integration (needs network)
npm run gen:tools                      # regenerate mcp/tools.json
Build & use
# build lib/ (tsc, NodeNext ESM; ships .js + .d.ts)
cd quant-indicators && tsc -p tsconfig.json

# use in dsh: add one line to cordis.yml
# - name: 'dsh-quant'
# (the Loader resolves the package exports → lib/index.js from node_modules)
Verification
# pure-function numeric correctness + market parsing + backtests (174 cases, node:test, zero deps)
cd deepseek-harness && pnpm exec tsx --test ../quant-indicators/tests/*.spec.ts

# REAL-composition: cordis.yml booted through the real Loader (registration visible / pipeline / isError / HMR-safety)
cd deepseek-harness && pnpm exec tsx --test ../quant-indicators/tests/loader-composition.spec.ts

# harness integration (schemas → execution pipeline → isError → live fetch→indicators→backtest end-to-end)
cd deepseek-harness && pnpm exec tsx ../quant-indicators/verify.ts

# consumer simulation: built lib loaded through real node_modules resolution (simulates post-install)
cd deepseek-harness && pnpm exec tsx ../quant-indicators/consumer-test/boot.ts
⭐ Support
If dsh-quant helps your research, a ⭐ makes the project visible to more dsh users.

This whale stands for DeepSeek Harness (dsh) — trading on its holographic screen 🐋
Issues / PRs / discussions welcome; share your domain perspective in Discussion #10. 🐋
Ecosystem infrastructure: quant ecosystem directory · ecosystem playbook · ecosystem map Discussion #11
Research columns: quant-history (firm archives) · quant-repo (open-source special)
Plugin library (five slots × external repos & MCPs): plugin/
Frequently Asked QuestionsFAQ
Use the verified command dsh plugin --profile default add github:pengpengyi92/dsh-quant in a DSH-enabled shell. The command resolves the public package metadata and keeps the plugin attached to the catalog identity shown on this page.
Compatibility follows the bundle and profile status shown above. If a profile is not detected, keep the plugin disabled there and check the repository documentation before enabling it in production.
The GitHub link and activity metadata are the source of truth for releases and maintenance. Revisit this page after a new release to confirm the catalog has observed the latest version.